
Our client became aware that their property could have unnecessarily had the higher rates of Land Transaction Tax (“LTT”) applied to it at completion. Previously the client had spent some time researching the topic at a high level. We were asked to advise on the LTT position. The position being the Stamp Duty Land Tax (“SDLT”) equivalent in Wales. This is managed by the Welsh Revenue Authority (“WRA”).
This is a common occurrence which shows across a number of solicitors. Luckily, this was presented to us within the 12-month period following the Client buying the property. Allowing a submission for a LTT reclaim to the WRA.
Ordinarily, residential properties are subject to the standard residential (or higher) rates of LTT. This depends on whether the purchaser owns other residential property. However, you should note a transaction is a non-residential transaction if any part of that transaction consists of or includes non-residential property. Where this is the case, the non-residential rates of LTT apply when calculating the LTT payable.
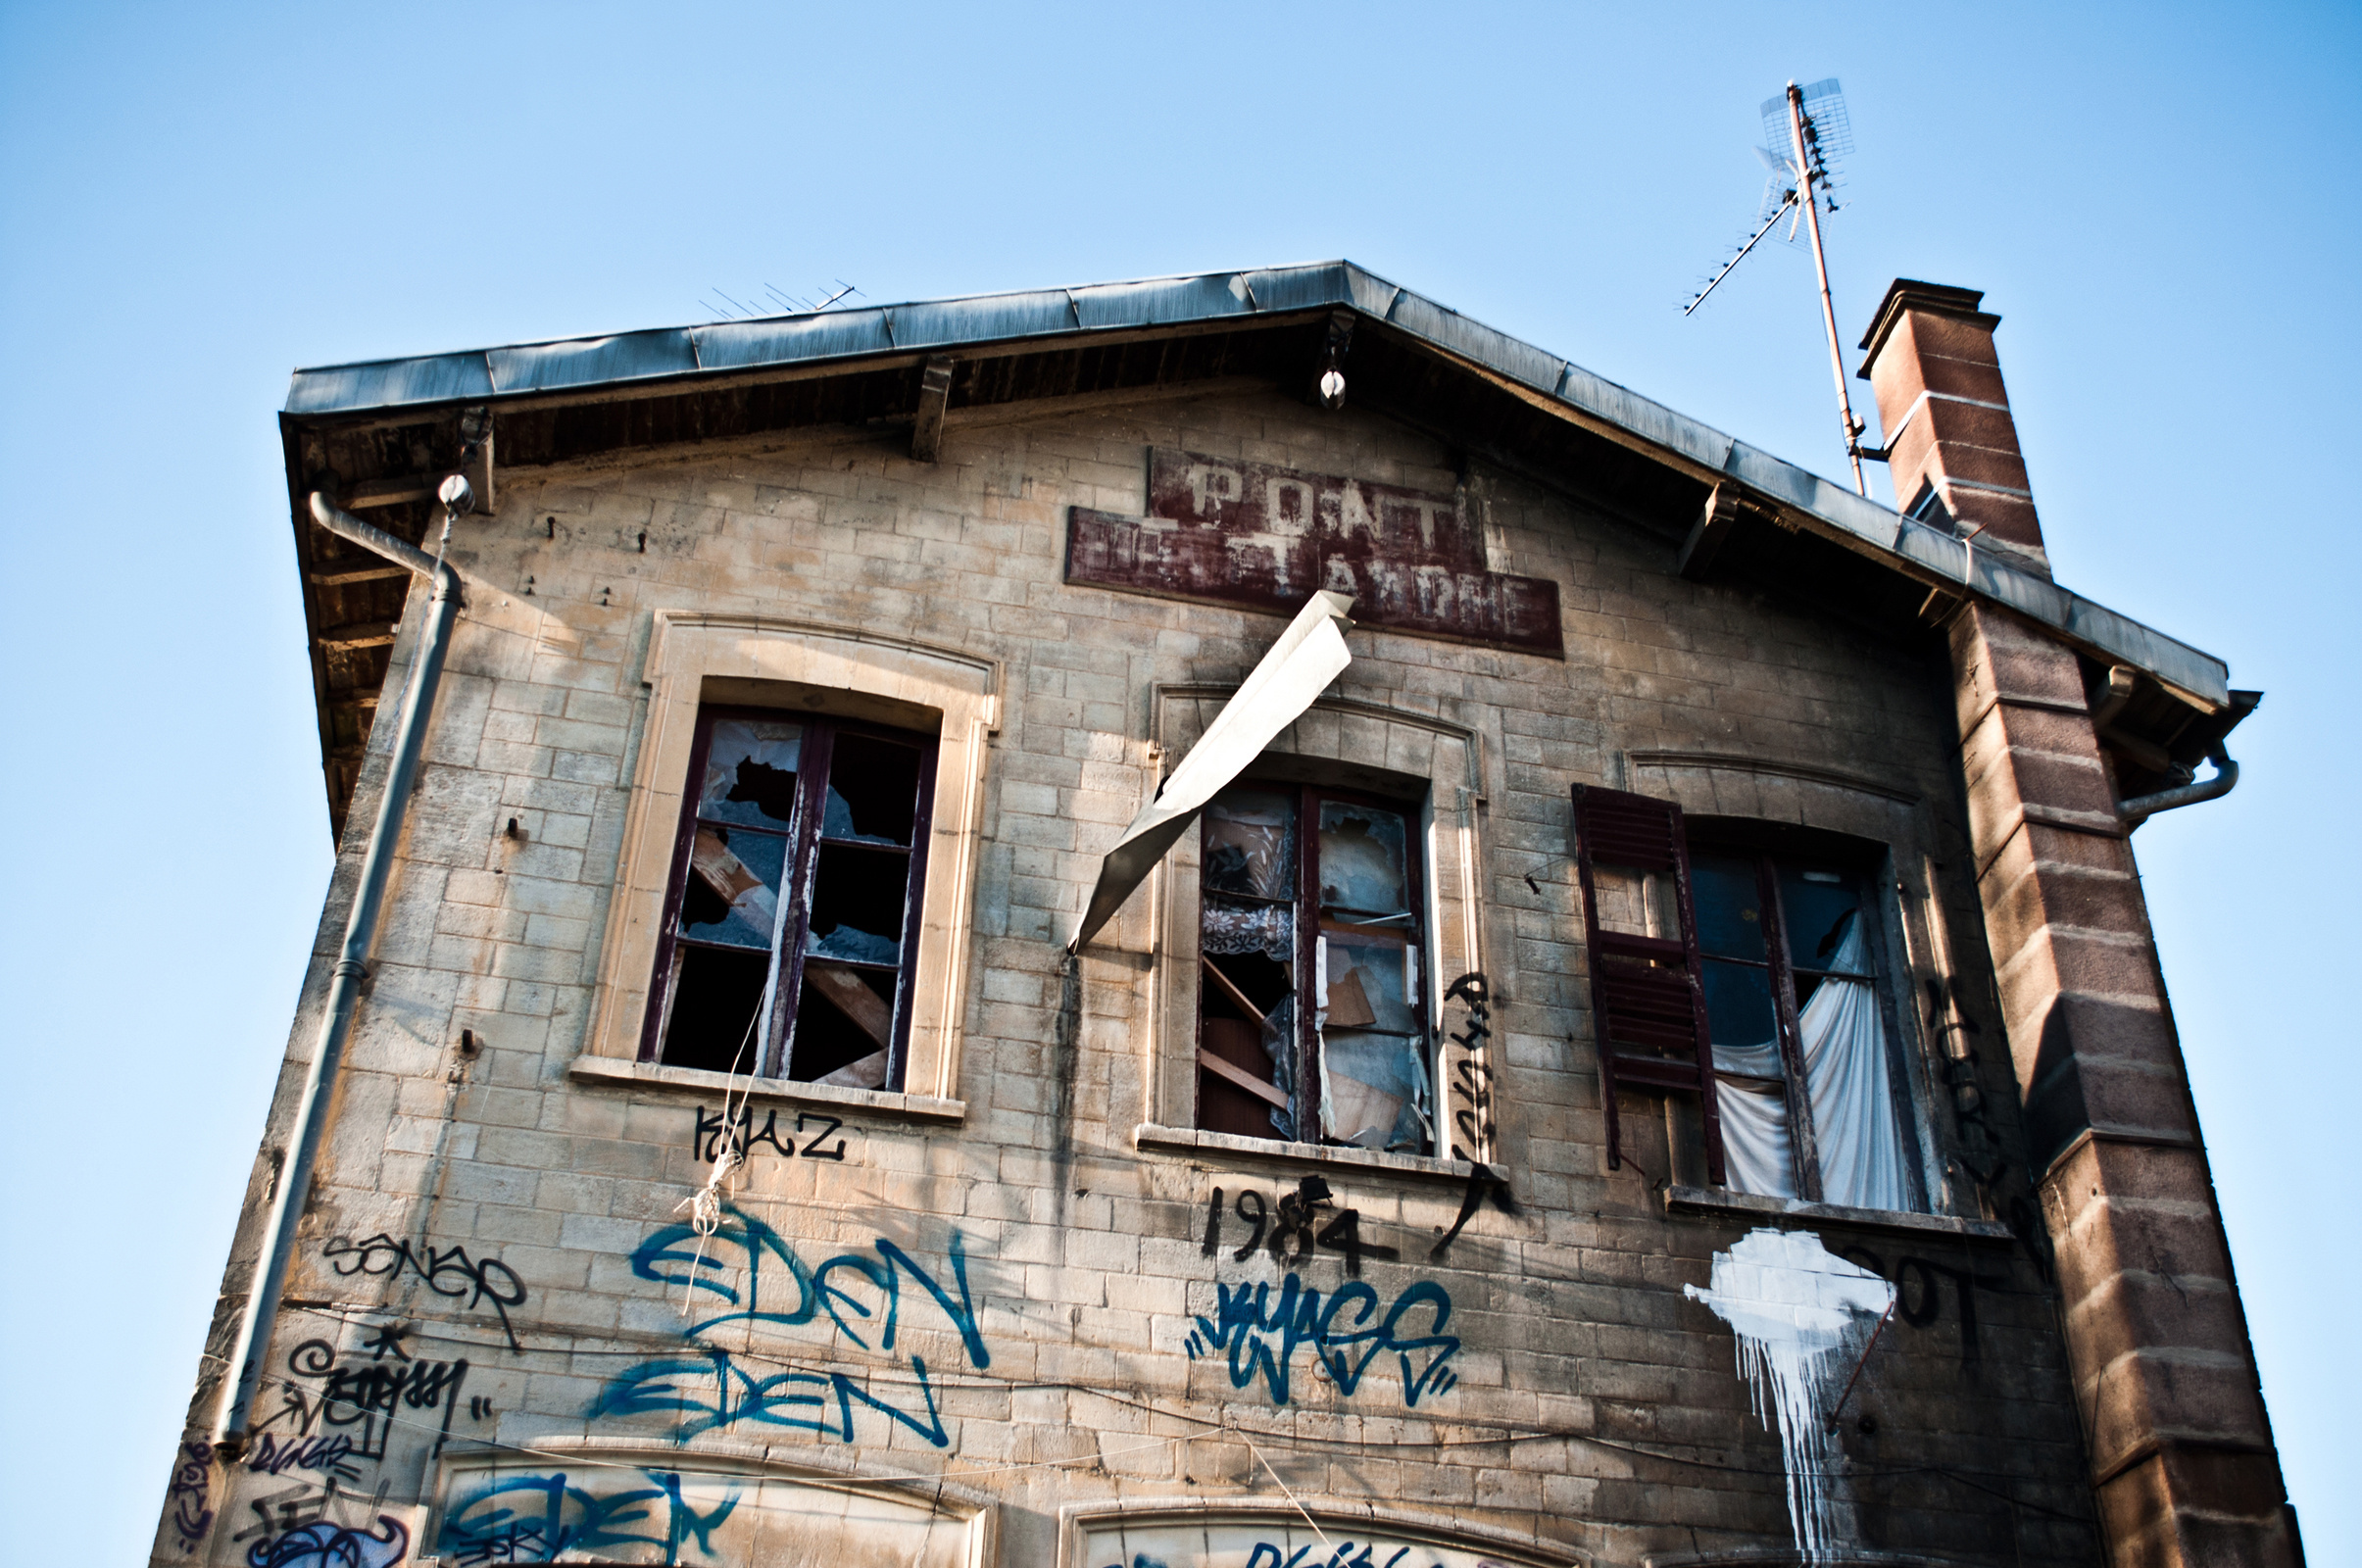
In this case, a report carried out by the property surveyors detail the condition of the building was a strong supporting factor in arriving at the non-residential conclusion. Summing up, this can be extremely helpful (though not necessary) when trying to determine how to treat a transaction for LTT purposes. It is supporting evidence where the WRA look to issue an enquiry into the LTT return.
It was important to consider whether the property was suitable for use as a residential dwelling. Following on from this, particularly consider at the point you complete. Additionally, we had a look at whether the property was in the process of construction. Alternatively, if the property is having adaptations for use as a dwelling. Considering the law above and the WRA’s view (or HMRC’s view if the property is in England), all take into account on what is now a complex area of taxation.
Quite importantly, the key consideration is the state of the property at the date of completion. HMRC have past attempts to place reliance on whether renovations can apply to the property. This could later be used as a dwelling at a later date as seen in the First-tier tribunal (FTT) case PN Bewley Ltd V HMRC. Here, the FTT said that when considering the SDLT position, they can’t rely upon potential renovation when analysing the property at completion and therefore they agreed with the taxpayers position.
In this particular LTT case, we aided the taxpayer by providing them with a formal LTT report. The report confirms the LTT position and we then made an application to the WRA to reclaim the LTT overpaid. This led to a recovery of over £7,000 of overpaid LTT for the taxpayer.
Please note that each case has its own variations. Therefore, seek advice on each particular case. This ensures advice is based on the facts and information.
If you have any queries, please get in touch.
 Optimized by Seraphinite Accelerator


